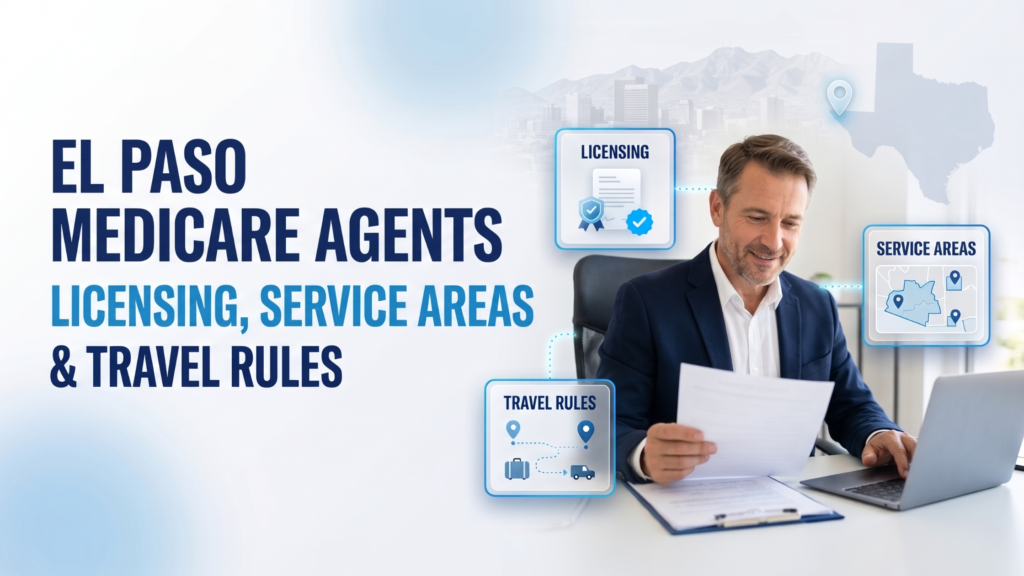
El Paso Medicare agents serving borderplex clients need three things right: a license and carrier appointments in the client’s state of residence, plans matched to the county where the client permanently lives, and accurate answers on care in Juárez. A good Medicare FMO gives agents a clear playbook for New Mexico licensing, service-area moves, and travel coverage conversations.
Here’s the thing: the El Paso market doesn’t stop at the state line. Your client in the Upper Valley has a daughter in Las Cruces. Your Eastside client spends half the winter at a sister’s place in Sunland Park. Your Northeast client crosses into Juárez for dental work, and a Socorro couple splits time between Horizon City and family across the river.
That’s normal borderplex life. But licensing, service areas, and coverage outside the U.S. all follow specific rules. Let’s walk through them.
Do you need a New Mexico license to help clients in Las Cruces or Sunland Park?
Generally, yes. If the client’s permanent residence is in New Mexico, you need a New Mexico license and the right carrier appointments before you discuss or enroll them in a plan. Your Texas license covers Texas residents, not where the client happens to be sitting during the appointment.
CMS says agents and brokers must be licensed in the state where they do business (CMS Agent Broker Compensation). Federal rules also require agents representing MA organizations to be licensed and appointed under state law where the state requires it (42 CFR 422.2274).
For New Mexico, the Office of Superintendent of Insurance says nonresident producers must hold an active resident license first, can only get the same license types and lines of authority they hold at home, and apply through NIPR (NM OSI Individual Licensing Instructions).
A practical sequence:
- Get the nonresident license for New Mexico through NIPR.
- Request New Mexico appointments with each carrier you’ll offer there.
- Finish certification for any New Mexico products you’ll present.
- Don’t run a New Mexico appointment until all three are confirmed in writing.
Not licensed there yet? Refer the client to a licensed colleague.
Why does the client’s permanent address decide which plans you can show?
Medicare Advantage and Part D plans are approved by service area, typically county by county, so the client’s permanent residence sets what’s available. An El Paso County address and a Doña Ana County address can have completely different options. Where the client gets care doesn’t change that.
CMS enrollment guidance says a person is eligible to enroll in an MA or Part D plan if they permanently reside in the plan’s service area (CMS CY 2027 Enrollment and Disenrollment Guidance).
You’ve probably seen this: a client lives in Canutillo or Anthony, Texas, but sees doctors in Las Cruces, or a Santa Teresa client uses West Side specialists. You quote for where they live, then check networks for where they go.
Never suggest a client use a relative’s address in another county or state to get a different plan. Misstating residency is a compliance problem for you and a coverage problem for the client.
What happens when a client moves to Doña Ana County or stays away for months?
A permanent move out of the plan’s service area generally gives the client a Special Enrollment Period (SEP) to choose new coverage; if they don’t pick a new Medicare Advantage plan, they land in Original Medicare. Long absences are different: an MA member out of the service area more than six months in a row can generally be disenrolled. Start both conversations early.
Medicare.gov says the chance to switch starts when the client moves and runs for 2 full months after. If they tell their plan before moving, it starts the month before the move and runs 2 full months after (Medicare.gov Special Enrollment Periods).
What to do:
- Ask every review client about planned moves, even “maybe next year, near my son in Las Cruces.”
- Document the move date and new address, and check licensing first if it’s New Mexico.
- Set follow-up tasks so the SEP window doesn’t close quietly.
On long absences, CMS guidance says a member may stay enrolled if the MA organization offers a visitor or traveler program for members consecutively out of the area for more than six months but less than 12 months (CMS CY 2027 Enrollment and Disenrollment Guidance). Those programs vary by plan, so check the specific plan. If a client says they’ll be “mostly in Juárez with my mom this year,” review the plan’s rules with them and document it.
What should agents know about care and prescriptions in Juárez?
Original Medicare generally doesn’t cover care outside the U.S., and Medicare drug plans don’t cover prescriptions bought outside the U.S. Some Medigap plans include limited foreign travel emergency coverage, and MA plans may cover some care abroad, depending on the plan. Explain the rules accurately; don’t promise coverage.
The specifics, from official sources:
- Original Medicare. Medicare.gov says Medicare usually doesn’t cover care outside the U.S. and lists rare exceptions, such as when a foreign hospital is closer than the nearest U.S. hospital that can treat the client (Medicare.gov Travel Outside the U.S.).
- Part D. Medicare.gov says Medicare drug plans don’t cover prescription drugs bought outside the U.S. (Medicare.gov). That matters for clients filling prescriptions at Juárez pharmacies.
- Medigap. Medicare’s coverage-outside-the-U.S. publication says Plans C, D, F, G, M, and N (and discontinued E, H, I, and J) include foreign travel emergency coverage. It pays 80% of billed charges for certain medically necessary emergency care after a $250 yearly deductible, has a $50,000 lifetime limit, and applies only to care that begins in the first 60 days of a trip (Medicare Coverage Outside the United States).
- Medicare Advantage. The same publication says MA plans may cover extra services outside the U.S., and members should check with their plan (Medicare.gov publication 11037). Look it up in the Evidence of Coverage (EOC) for each plan. Never assume.
How do you run borderplex appointments with family decision-makers?
Run them in the client’s preferred language, with the right family members in the room, and with every residency and travel detail written down. In El Paso, an adult child often joins by phone from Las Cruces or helps with paperwork. Respect that, but the beneficiary makes the decision.
A few habits that hold up:
- Offer Spanish and English from the first call, with a licensed bilingual agent where possible.
- Confirm the permanent address with a document the client already has, and note it in the file.
- Ask about travel patterns: how often they cross, how long they stay, where they fill prescriptions.
- Map their providers. Many El Paso clients use University Medical Center of El Paso, Texas Tech Physicians, The Hospitals of Providence, Del Sol, or Las Palmas. New Mexico clients may use MountainView or Memorial Medical Center in Las Cruces. Verify networks for each plan; don’t assume.
- Note other coverage. Military retirees near Fort Bliss and veterans using VA care need those benefits recorded so you can see how everything fits together.
That’s our training philosophy: get the facts right before any plan discussion, and document the reasoning.
Which Texas FMOs give El Paso agents the right support?
Look for an FMO that helps you handle cross-state licensing, county-level service areas, and travel coverage questions, plus the CRM to document it all. Here’s a neutral look at five FMOs active in Texas.
1. TMS Insurance Brokerage (Texas Medicare Solutions)
A Texas-based FMO with statewide reach, headquartered in San Antonio, supporting agents in El Paso and across Texas both remotely and in person.
- Best for: Independent agents who want hands-on coaching on Texas-specific markets like the borderplex, without volume gates.
- Strengths: Free OmniReach CRM (GHL snapshot), a dedicated Agent Success Manager, up to $900/month in Brokerage Bucks marketing reimbursement, the Medicare Agent IQ podcast, and familiarity with Texas carriers, demographics, and regulators.
- Limitations: Built around Texas. If a large share of your book is in New Mexico, ask about nonresident contracting support up front.
2. Integrity Marketing Group
National aggregator.
- Best for: Agents who want a large platform with built-in technology.
- Strengths: MedicareCENTER tools, scale, and wide carrier access.
- Limitations: Support quality depends on the partner agency.
3. AmeriLife
Multi-line distributor.
- Best for: Agents adding life, annuity, and final expense alongside Medicare.
- Strengths: Established training and multi-line resources.
- Limitations: The broad focus can mean less time on border-market nuances.
4. Senior Market Sales (SMS)
Established national back office.
- Best for: Agents who want a stable, long-running platform.
- Strengths: Long carrier relationships and solid quoting tools.
- Limitations: A larger organization usually means less one-on-one attention.
5. Ritter Insurance Marketing
Tech-forward, self-directed model.
- Best for: Agents who like to learn on their own.
- Strengths: A large content library and a clean digital experience.
- Limitations: Less hands-on, Texas-specific support.
If you’re weighing a move, read our guide on how to switch FMOs safely before you change anything mid-season.
What’s my AEP-week checklist for borderplex clients?
Use AEP week to confirm residency, licensing, and travel patterns for every client who has ties on both sides of a state line or the border. Sort your book first, then work the list.
- Tag cross-state clients in your CRM: El Paso residents with New Mexico ties, and New Mexico residents you serve.
- Confirm your New Mexico license and appointments before booking any Doña Ana County appointment.
- Verify each client’s permanent address and note the source.
- Flag pending or recent moves and track SEP dates.
- Note long absences and check each plan’s out-of-area and visitor/traveler rules.
- Check EOCs for coverage outside the U.S. for clients who travel to Juárez often.
- Remind clients that Part D doesn’t cover prescriptions bought outside the U.S., and point them to Medicare.gov.
- Confirm bilingual coverage and Spanish-language materials.
- Audit SOA, TPMO disclaimer, and call-recording steps.
Our free Medicare CRM, OmniReach, can handle the tagging, date tracking, and permission-based follow-ups, and the Medicare Agent IQ podcast covers real-world situations like these.
If you’re an El Paso agent and your current FMO doesn’t have a borderplex playbook for licensing, service areas, and travel coverage conversations, let’s talk. TMS Insurance Brokerage is a Texas-based FMO with statewide reach — we help independent agents build durable books without volume gates.
 English
 Spanish